


Converting a traditional IRA or another qualified retirement plan to a Roth IRA can be a powerful wealth-transfer tool under the right circumstances. Knowing and quantifying the “right circumstances,” however, can be a daunting task.
In this paper, we will look at how a Roth conversion works and identify the factors that need to be considered when deciding whether converting to a Roth makes sense for you.
How does a Roth IRA conversion work?
Before exploring the mechanics of converting a traditional IRA to a Roth IRA, it is important to understand the difference between the two types of retirement accounts.
Traditional IRAs (pay taxes later) vs. Roth IRAs (pay taxes now)
The difference between traditional IRAs and Roth IRAs comes down to whether you pay taxes on the front end (on the contributions) or the back end (on the distributions). With a traditional IRA, contributions to the account are often tax-deductible, but once you withdraw the funds, the distributions, including any growth of those funds, are fully taxable as ordinary income. With a Roth IRA, on the other hand, the timing of when you pay is reversed. There is no up-front tax deduction for contributions to a Roth IRA, but qualified distributions are tax-free, including any growth of your contributions. These tax-free distributions apply not only to the Roth IRA’s original owner but also to any heirs who may inherit the account.
No RMDs for Roth
Besides tax-free growth, another advantage of Roth IRAs is the lack of required minimum distributions (RMDs). With a traditional IRA, the account owner is required to start taking distributions upon reaching age 73 or 75. [1] This requirement does not apply to Roth IRAs, and the lack of RMDs can make Roth IRAs powerful estate planning and wealth accumulation tools.
Taxes: The cost of converting
Converting a traditional IRA to a Roth IRA often creates a significant one-time tax bill for the account owner. When converting an IRA, any funds representing contributions that were tax-deductible, as well as the growth of those contributions, are taxed as ordinary income in the year of the conversion.
For example, if an investor in the 37% bracket converts a traditional IRA worth $1 million to a Roth IRA, the investor would owe $370,000 in taxes that year. (This assumes that 100% of the investor’s contributions to the traditional IRA were tax-deductible.)
It is important to note that the income generated by a Roth conversion can trigger the 3.8% Medicare surtax on unearned income, which hits single filers with modified adjusted gross income (MAGI) greater than $200,000 and married filers with MAGI greater than $250,000. The conversion amount itself is not counted as unearned income, but the conversion amount is included in MAGI. As a result, more of your unearned income may be subject to the Medicare surtax.
Recharacterizing a conversion
Prior to 2018, it was possible to undo, or “recharacterize,” a Roth conversion. If the market value of the account decreased soon after the conversion occurred, it may have made sense to recharacterize the account back to a traditional IRA and then do another Roth conversion later on. Doing so may have allowed you to have a lower tax bill for the conversion because the size of the account may have been smaller after the market dip.
The opportunity to recharacterize a Roth conversion is no longer an option.
Variables to Consider for a Roth Conversion
Although there are no hard-and-fast rules for whether or not to convert a traditional IRA to a Roth IRA, a conversion usually creates the most value when the investor:
- Anticipates being in a higher or equivalent bracket during retirement
- Will not need to make withdrawals from the account in the short term
- Has funds available outside the IRA to pay for the conversion tax
- Plans on having a significant balance in the account to pass onto heirs
Is a Roth Conversion Right for You?
Under the right circumstances, converting a traditional IRA to a Roth IRA can create significant tax savings and valuable wealth-transfer opportunities. But these circumstances certainly won’t apply to all investors. It is important to understand the variables that determine whether a Roth conversion makes sense.
Time to recoup conversion costs
The up-front tax expense of a Roth conversion is offset by the opportunity for tax-free growth after the conversion. The more time you have until you need to withdraw the funds, the better the chances that the tax-free growth will outweigh the up-front tax bill.
Expectations for future income tax rates
In deciding whether to convert to a Roth IRA, you are really seeking to answer the following question: “Should you pay income tax now or later?” The answer to this question depends, in part, on whether your tax bracket during retirement will be higher or lower than your current tax bracket. Although it is impossible to predict what Congress will do with tax rates down the road, we do know that the top marginal tax rate of 37% is near the historical low. One strategy for hedging against the uncertainty of where tax rates are headed is to convert a portion of the account to a Roth IRA and leave the rest as a traditional IRA. This strategy diversifies your exposure to tax rates.
Top Marginal Tax Rate at Retirement
Your expectations for whether you will be in a higher or lower tax bracket during retirement is a major factor in the Roth conversion decision.

Availability of cash to pay tax on conversion
Investors considering a Roth conversion need to think about where the cash will come from to pay for the tax bill generated by the conversion. If you are able to pay the tax using resources outside of the IRA, it will significantly increase the chances that the conversion will provide a net benefit. If you have to liquidate assets in the IRA to pay for the conversion tax, however, that will significantly eat into the potential benefits of a conversion. In addition, if you are not yet age 59 1/2, you will be subject to a 10% early withdrawal penalty.
Intended use of the funds
How you intend to use the funds can also help determine whether a Roth conversion makes sense.
If you plan to make significant charitable donations, it may be more beneficial to keep a traditional IRA to fund your charitable planning goals. On the other hand, if you do not anticipate needing to tap into the IRA during your lifetime, then you would likely benefit from a conversion. The lack of required minimum distributions and the opportunity for tax-free distributions make Roth IRAs a powerful wealth-transfer tool.
Fortunately, Roth conversions are not an all-or-nothing proposition. You could, for example, convert the portion of your IRA that you intend to pass to your heirs and leave the portion earmarked for charitable contributions in the traditional IRA. It should be noted, however, that the tax on the conversion is based on a weighted average of all contributions to the IRA; you can’t simply convert the assets that would incur the lowest tax liability.
Measuring the Benefits of a Roth Conversion
We have constructed the following hypothetical scenario to help quantify the potential benefits of converting a traditional IRA to a Roth IRA.
In our example, a 65-year-old investor in the 37% tax bracket has $1 million in a traditional IRA and $370,000 in a taxable account. The investor has three options:
- Option A: Keep the retirement account as a traditional IRA
- Option B: Convert the traditional IRA to a Roth IRA and pay the tax on the conversion using funds from within the IRA
- Option C: Convert the traditional IRA to a Roth IRA and use funds from the taxable account to pay for the tax on the conversion
The chart below shows the total value of the investor’s portfolio after 30 years under each of the three options.
Portfolio After 30 Years
Analysis assumptions: These results assume annual investment returns of 6%. In Option A is a 65 year old investor and was required to begin taking required minimum distributions at age 73, and the after-tax distributions are deposited in the taxable account.
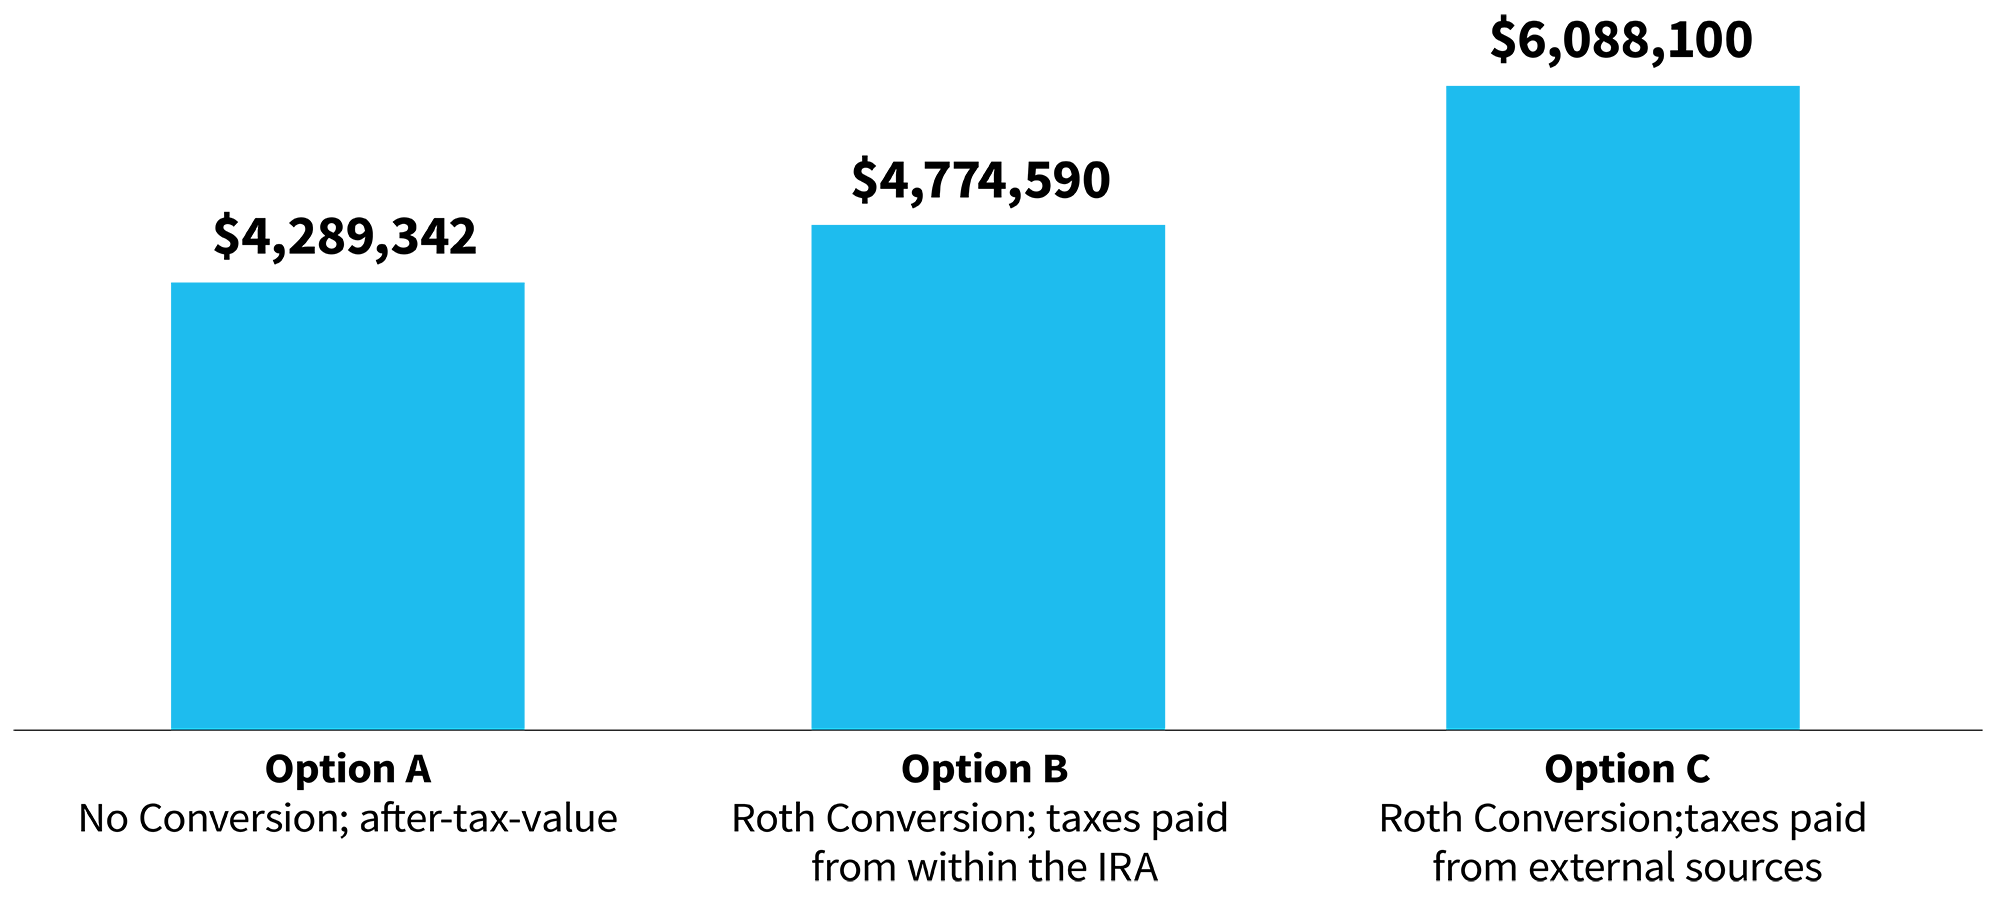
Back Door Roth Strategy
For high-income earners who exceed the IRS income limits for direct Roth IRA contributions, the Backdoor Roth IRA strategy offers a valuable alternative. This approach involves making a non-deductible contribution to a Traditional IRA and then immediately converting those funds to a Roth IRA. While the contribution itself is not income-limited, the subsequent conversion allows investors to benefit from the Roth IRA’s key advantages: tax-free growth, tax-free qualified withdrawals, and no required minimum distributions during the account owner’s lifetime.
One important consideration when implementing a backdoor Roth strategy is the Pro-Rata Rule, which governs how taxes are calculated on Roth conversions. If an investor holds both pre-tax and after-tax dollars across any Traditional IRAs, SEP IRAs, or SIMPLE IRAs, the IRS requires that conversions be taxed proportionally based on the total balance of all such accounts. This means you cannot isolate and convert only the after-tax (nondeductible) contributions to avoid taxation. For example, if 60% of your total IRA balance is pre-tax and 40% is after-tax, then 60% of your conversion will be taxable. This rule can significantly impact the tax efficiency of a backdoor Roth strategy and should be carefully evaluated before proceeding.
Distributions After Account Owner’s Death
If your spouse inherits your traditional IRA, he or she can treat the account as if it is their own and begin taking required minimum distributions at age 73 or 75, depending on their age. With a Roth IRA, the spouse is not required to take any withdrawals during their lifetime, enhancing the tax-free growth of the balance that remains in the account.
With the passage of the SECURE Act in 2019, most nonspouse beneficiaries must fully distribute the inherited IRA, whether traditional or Roth, within 10 years. Previously, distributions could be “stretched” and taken over the life expectancy of the non-spouse beneficiary. [2]
If they inherit a traditional IRA, the same distribution rules apply, but income tax must be paid on every distribution. Under this legislation, it may be even more advantageous to pass along Roth IRA assets as opposed to traditional IRA assets to reduce the tax liability for the beneficiary.
The case for a conversion becomes even more compelling when you consider estate taxes
Roth IRAs can be powerful wealth transfer vehicles, under the appropriate circumstances, because of the ability to “prepay” income taxes and the lack of required minimum distributions for the account owner. Income tax due on the conversion acts as a gift to the beneficiaries because they will not have to pay income tax on qualified distributions. Furthermore, the amount paid for income tax upon conversion is removed from the original account owner’s estate.
Planning for a Conversion
Converting a traditional IRA to a Roth IRA can provide significant long-term tax savings and serve as a powerful tool for transferring wealth to future generations. Whether a Roth conversion makes sense for you, however, depends on your timeframe, your expectations for future tax rates, your plans for the assets, and your available resources.
William Blair can work with you to evaluate whether a Roth conversion is appropriate for you in light of these variables and your retirement and wealth-transfer goals. Please contact us to schedule a time to discuss whether you should consider a Roth conversion as part of your comprehensive wealth management strategy.
Roth IRA Conversion Questionnaire
| Can you afford to leave the IRA untouched throughout retirement, funding your expenses through other sources of income instead? | Yes | No |
| Will you be in the same or a higher tax bracket in the future? | Yes | No |
| Can you pay the tax on the conversion by using funds from outside the IRA? | Yes | No |
| Can you convert without negatively affecting your current income tax planning? | Yes | No |
| Can you continue to fulfill your other financial planning objectives (e.g. charitable giving)? | Yes | No |
| Your wealth-transfer plan will likely benefit from a Roth conversion. | You may still benefit from a Roth conversion, but is advisable to run a personalized cost-benefit analysis. |
- Due to the SECURE 2.0 Act, the RMD age has increased to age 73 for individuals born in 1959 or earlier and to age 75 for individuals born in 1960 or later. ↩
- The 10-year distribution applies to most non-spouse inherited IRAs (traditional and Roth) when the account owner dies after December 31, 2019. ↩
Disclosure
This content is for informational and educational purposes only and is not intended to provide or should not be relied upon for legal, tax, accounting, or investment advice or a recommendation to buy or sell any security. Investment advice and recommendations can be provided only after careful consideration of an investor’s objectives, guidelines, and restrictions. We recommend that you consult your attorney, tax advisor, investment or other professional advisor about your particular situation. Any investment or strategy mentioned herein may not be suitable for every investor. Factual information has been taken from sources we believe to be reliable, but its accuracy, completeness, or interpretation cannot be guaranteed. Information or opinions expressed are current as of the date appearing in this material only and are subject to change without notice.